The Hidden Cost of “No Payments for 24 Months”
How deferred-payment ADU loans can quietly consume your equity
By the ADUabl Team
Ads promising “No Payments for 24 Months” make ADU financing sound effortless. But the payments are not forgiven—they are usually added to the loan through an interest reserve, increasing your debt before construction is complete.
Potential bait-and-switch concern: If an advertisement prominently promotes “no payments” but does not clearly disclose that the deferred interest and fees will be added to the loan—or if borrowers are later steered into a materially different product—the practice may raise bait-and-switch or deceptive-advertising concerns. Whether it constitutes a violation depends on the full advertisement, disclosures, loan terms, and applicable law.
The Illusion of “Free” Deferment
The lender estimates two years of interest, adds it to the loan, and pays itself monthly from those borrowed funds. You delay out-of-pocket payments, but finance them at a premium.
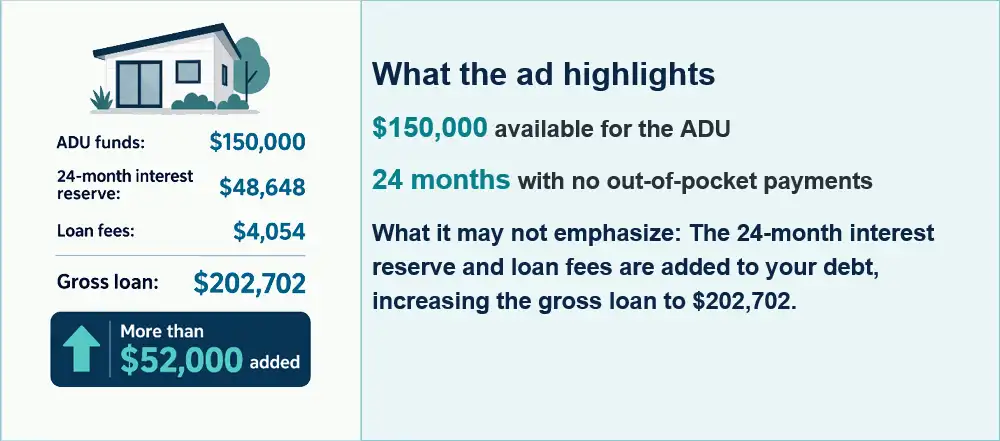
The Math: More Than $52,000 Added
Assume you need $150,000 for your ADU. At 12% interest with 2 points, a 24-month reserve pushes the gross loan to $202,702, more than $52,000 in added interest and fees.
The Qualification Trap
The inflated balance can also make the advertised loan harder to qualify for. Many specialized lenders cap combined loan-to-value (CLTV) at 70%–75% of the home’s current value.
The risk: If the reserve pushes you above the CLTV limit, the lender may redirect you to a standard HELOC or refinance—after you have already spent time pursuing the advertised program.
The Smarter Way to Build: Preserve Your Equity
Our approach: As a licensed mortgage broker, we take our fiduciary responsibility seriously and focus on finding the most suitable rate and terms for each client.
Compare transparent options that protect equity and match the project:
- Second-lien loans: Competitive rates and terms that can rival first-lien financing.
- Construction-to-permanent loans: Pay interest only on funds drawn during construction.
- Renovation loans: FHA 203(k) or HomeStyle financing may use the home’s future value.
- Shorter custom reserves: A 6–9 month reserve may provide flexibility with less added debt.
Run Your Own Numbers
Before signing, compare the gross loan amount, reserve cost, fees, CLTV limit, and long-term payment—not just the advertised payment delay.
Use the ADUabl Calculator to compare an interest-reserve loan with a standard construction loan using your project costs.
An ADU can be a strong investment—when the financing preserves the equity you are building.
Ready to compare transparent ADU financing options?
Contact the ADUabl team.
The 24-Month "No Payment" Ad
Deferred Payments for 2 Years
Standard Construction-to-Perm
Pay Monthly During Build